Three Working Days Before the Golden Week Break: Should This Shipment Go Now or Wait?
Five typhoons in a single summer left East China's two busiest hub ports badly backed up. The backlog is draining now, but far more slowly than most shippers assumed when they first saw the closure notices in late August. With the National Day holiday starting on 1 October, cargo owners face one practical question: push this consignment out in the next few working days, or hold it until after the break.
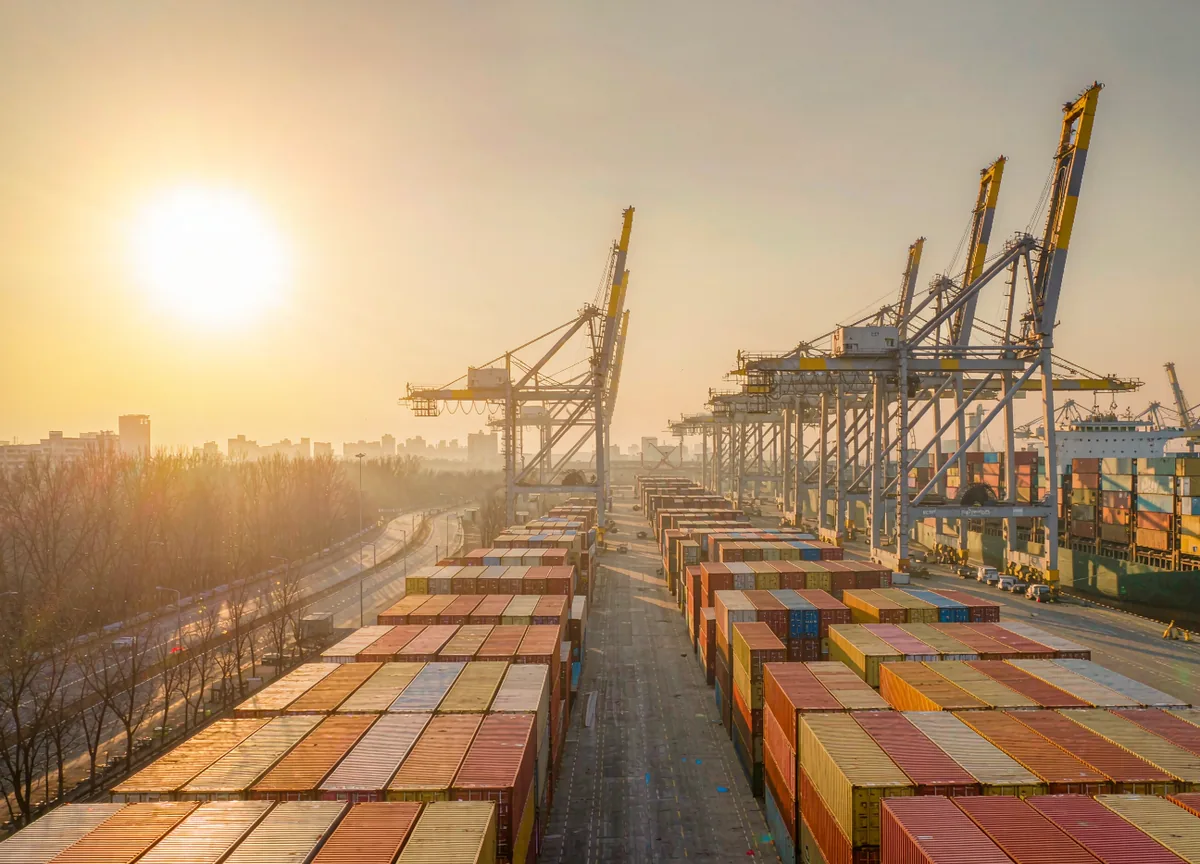
Start with the congestion ledger. Typhoon Saudel made landfall on the Fujian coast on 27–28 August, closing container terminals at Shanghai and Ningbo-Zhoushan from 26 to 29 August. Ningbo went on to accumulate 78 hours of stoppages over the following week as typhoon controls and fishing-vessel restrictions piled up; Yangshan lost 54 hours and Waigaoqiao 48. By early September Shanghai's seven-day average berth waiting time had reached 5.46 days, with several Waigaoqiao berths above nine days and close to a hundred vessels riding at anchor for a slot. Estimates from the Shanghai International Shipping Institute put the combined backlog awaiting clearance at around 400,000 TEU.
Seen globally, the picture is more sobering. Linerlytica counts more than 4.3 million TEU of vessel capacity waiting for berths worldwide, above the previous 4.0 million peak and a new record, with North East Asia accounting for 54% — roughly 2.5 million TEU. Sea-Intelligence estimates that berth delays are absorbing 6.6% of the global container fleet; even at the best historical recovery pace of 0.5–0.6 percentage points a month, returning to the June 2025 low would take four to six months. In other words, this is not a two-week weather event but a structural capacity gap running through peak season.
What makes September unusual is that rates did not follow congestion higher. The market has split. On the transpacific, Drewry assessed Shanghai–Los Angeles at about $7,185 per 40ft on 3 September, roughly 5% up week on week, and Shanghai–New York at about $9,587, up 3%; Xeneta put Asia–US West Coast above $7,295 per FEU in week 35, more than 20% above the previous week. Asia–Europe ran the other way: Shanghai–Rotterdam around $4,092, down 5%, and Shanghai–Genoa around $4,368, down 10%.
For shippers moving cargo through Europe, the Middle East, Africa and Southeast Asia, that divergence points somewhere specific. Europe and Mediterranean trades are the only major lanes still conceding price in the middle of a congestion shock, and several carriers are quietly discounting to fill ships. If European volumes are still tied to contract rates agreed earlier this year, this is the window to reopen that conversation. If you move cargo spot by spot, locking in part of your fourth-quarter requirement at these levels carries a favourable risk profile.
Transhipment deserves separate attention, because it hits Middle East, South Asia and East Africa routings hardest. Colombo has been squeezed from three sides — diverted Gulf volumes, limited deep-water berths and high winds — pushing vessel turnaround at the CICT and CWIT terminals to as much as six days, with inter-terminal transfer backlogs reported as high as 53,000 TEU. Hapag-Lloyd has warned of 48–72 hour delays and omitted calls, and the Mette Maersk skipped Colombo entirely, discharging at Singapore instead. Add a 48–72 hour buffer to anything routed through that port, and confirm with the consignee in advance whether a change of discharge port is acceptable.
So: ship now, or hold?
Three cases. First, machinery, building materials and out-of-gauge project cargo already booked on a string, where the overseas buyer has a fixed delivery milestone — move it before the holiday. Schedule disruption now extends into October, and waiting converts one layer of uncertainty into two, with berth buffers running three to five days beyond normal. Second, general cargo for Europe without a hard deadline can be partly deferred. Europe-bound rates remain on a downward path, and as the backlog clears and effective capacity returns, October spot levels are unlikely to sit above today's. Third, Ningbo cargo that must sail on the current string needs watching at the yard: after Meishan's yard density passed 90%, the port imposed controls requiring carriers to keep local export shut-out ratios below 10%. That is not a pricing matter but an escalation of whether the box loads at all — have the shut-out liability clause confirmed in writing by whoever books it.
One closing note. Standard transit times should not be your planning baseline right now. Global schedule reliability was 56.4% back in July, and five consecutive typhoons landed on an already weak baseline. Plan backwards from the arrival date your customer requires and leave at least a week of slack in front of it. For project and engineering cargo with installation milestones attached, double that margin.